

Three entrepreneurs, three roads to America. Now it's about yours.
Forming a US company: the guide for your real business in America
Mount Bonnell Advisors has been active in the USA since 2008. I lived there for six years myself and I'm "over there" all the time. A professional globetrotter, you might say. Americans call it "boots on the ground" know-how, and you can put it to work for your US plans.
The internet, globalization and mobility make it possible: the US market is within reach for European entrepreneurs. And a second pillar outside the EU makes your business less dependent on the crises of a single continent. That makes it all the more important that you can rely on a partner for your US expansion who knows not only US tax law but also the day-to-day reality of doing business in the USA.
This guide walks through every formation question in order: entity type, state, formation and ongoing obligations, taxes, taking out profits, bank account, holding and visa. For each topic you'll find the essentials in a few paragraphs and the way to the detailed page.
1Entrepreneurs' stories

So you're planning to form a company in the USA.
Let me dive straight in with three very different US stories from my clients. Three German entrepreneurs who made the leap to the USA successfully. Three real biographies, three lives woven into America in different ways.
I invite you to let the impressions and ideas they spark sink in as you read:
1.1Story 1: Hannes and the dream factory
Hannes A. was born in Saxony, but when I met him he had already lived in London with his wife and children for many years. There he runs a successful film equipment rental business: film cameras, lighting, microphones and more. His customers are international film studios and production teams shooting in England.
What sets him apart: Mr. A. doesn't just rent out the gear, he also works as a camera operator with some of his specialty cameras and takes part in film productions himself.
From the day Mr. A. opened his shop and warehouse in London, he knew he would one day move to Los Angeles to work in Hollywood. It took him around ten years to make the London business a success (all with his own money). The whole time he had just one goal in mind: to work with the very best. To be part of the dream factory.
In 2014 he was finally able to form a subsidiary in the USA and move to the States with his whole family on an L-1 visa.
Mr. A. may work in the dream factory, but he's no dreamer: the London shop keeps running and pays for the family's living. He took part of the equipment, including the specialty cameras, to California and rents it out there.
He also works as a camera operator on a number of indie films. Mr. A. still has big plans, but he has already taken an important step.
1.2Story 2: Commuting between London and Miami
I met Mr. Udo F. in 2012. He was originally from Hamburg. One foggy November morning he walked into our London office to get my advice on English personal bankruptcy proceedings.
Mr. F. looked tired, and I assumed he'd had to get up early to catch the flight from Hamburg to London. As we talked, though, it turned out he had flown in from Florida that morning, where his family ran three restaurants. The debts he wanted to clear in England dated back to his time in Germany and had nothing to do with his US business. Now it was about cleaning up the past. A clean slate, so to speak.
Mr. F. breezed through the one year of residence in England that English consumer bankruptcy required. Rarely have I seen a client with a more optimistic and relaxed attitude toward life and the proceedings.
In between, he kept flying back to his family in Florida, or his grown-up daughters visited him in London. The thriving US businesses allowed his wife to act as his sponsor and finance his stay in England.
1.3Story 3: New York, New York
Ludger P. from the Sauerland region trades solar panels made in Asia on a large scale. It's a German company, but it ultimately sells worldwide. Sales run online, and customers are mostly consumers and installers. Revenue is in the high tens of millions.
When Mr. P. was planning the move, public subsidies for renewable energy in Germany and other European countries were being cut further and further. Dream tariffs for green power were gone for new installations.
Not so in the USA.
There, the topic was still at the start of a development that had been under way in Europe, especially Germany, for decades. Accordingly, the USA offered attractive incentive programs for large and small solar installations.
In 2013 Mr. P. decided to take the step into the USA. He opened a US branch of the German company in Upstate New York, where fifteen American employees work on growing the business in the States.
Mr. P. got an E-2 visa without any trouble. He has no plans to move to the USA, but longer stays of three to four months at a time matter while building the business, and as a single man that's no problem for him. He has rented an estate in the Hamptons and splits his time between Germany and New York.
2Your America story
What's your story? Where are you in life? What are your US plans? Do you see yourself in one of our three stories? Is the USA your dream destination, an escape, or simply an interesting market for your business?
No doubt you're giving serious thought to expanding into the USA, and it matters to you.
Whether the USA is a childhood dream, a secure second pillar or simply a big opportunity for you: on this page you'll find plenty of useful information that will hopefully help you along the way.
This page is tailored entirely to entrepreneurs like you who want to start doing business in the USA.
My team and I help make your America story a success. I lived in the USA for six years myself, I'm there regularly, and I've guided many clients on their way to the USA.
We've gathered a lot of facts for you here, because the topic is so broad and exciting. Still, information is no substitute for advice. If you're serious about the USA, I suggest a personal consultation where we can discuss your plans in depth.
3Assumptions
We wrote this page based on the following assumptions. If they don't apply to you, our offer may not be the right fit.
Here are our assumptions:
- You plan to form a US company to serve the American market.
- You expect revenue of at least $250,000 a year.
- You plan to set up an operation in the USA within 12 to 18 months of forming the company at the latest, with your own premises, employees and everything that goes with it.
- Optionally, you plan to move to the USA. A visa and green card are on your radar.
We are not a bargain formation service. This page is expressly not for people looking for the kind of service offered by various dubious US formation agencies. If you need a shell company in the USA, please use one of those providers. We clearly distance ourselves from such setups and strongly warn you about the half-truths you'll find in abundance on their websites.
4Background: why form a company in the USA at all?
Any way you look at it, the USA is a heavyweight of the global economy, and the dollar is the currency the world trades in. Until our children learn Chinese at school and we mostly watch Chinese films at the cinema, a few more decades will in all likelihood pass.
As our stories show, serving the American market from a US base is attractive for European entrepreneurs. Usually several considerations come into play:
- The USA as a second pillar: if you want to build another source of income far from Europe's trouble spots, the USA, with its size and purchasing power, is the logical choice.
- Living in the USA: Unless you are truly broke, the USA offers an exceptional quality of life and plenty of opportunity. There is a reason so many top people in science, medicine and business head to America: in these fields there are simply far more opportunities. And what better foundation for a US visa or green card than a US company?
- Expansion plans: If you already run a successful business in Europe, you will often find that expanding into the US market is far easier than conquering, say, three European markets. Why wrestle with Italy, Spain, Portugal, three languages and at least three cultures when the USA offers one huge economic area with one common business language?
That is the background against which we position our US services.
Mount Bonnell Advisors has been active in the American market since 2008. Since then we have helped many clients form and manage American companies, and we have built valuable hands-on knowledge of US corporate and tax law. Our local network of US accountants and attorneys means our clients have top expertise on hand whenever they need it.
From ongoing tax support for your US company to market entry: Mount Bonnell Advisors gives you professional support with every matter. Whether a separate company or a branch of your business is the better route is compared on the page Branch or subsidiary.
5LLC, Limited Partnership (LP) or C Corporation (Inc): what they really are
The most widely used legal forms in the USA are the Limited Liability Company (LLC) and the C Corporation (often called an "Inc."). We also recommend the Limited Partnership (LP) to our clients. There are a number of other forms (LLP, S Corp and more), but they are not relevant for most clients. An S Corporation, for example, may by law not have a shareholder who is a nonresident alien. The LLC without a permanent establishment in the USA is the topic of our sister site zerotax.llc.
All the features of each legal form described here apply regardless of the state in which the company operates.
5.1Common US legal forms at a glance
The overview sets side by side the three legal forms our clients use in the USA. The LLC combines limited liability with flexible taxation: without a special election, the IRS treats a single-member LLC as transparent and a multi-member LLC as a partnership; with Form 8832 it can elect to be taxed as a corporation. The C Corporation is the stock corporation of American law and pays its own tax, 21 percent federal tax on profit.
Which one fits depends on your plans and on how the company is taxed in the USA and at home. The overview applies to companies that do business in the USA and pay tax there.
5.2Which US legal form is best for me?
5.3Quick check: which US legal form is best for me?
The quick check matches typical starting points to a legal form. It assumes that all US legal forms offer the same liability protection, so tax is the deciding factor. For a startup planning an exit and for the subsidiary of a European company, the C Corporation fits; for a life in the USA, the LLC. If you have no business in the USA, you will find the right answer at zerotax.llc.
The check is deliberately simplified and is no substitute for a consultation. When in doubt, we recommend the C Corporation, because it leaves the fewest questions open.
5.4Sky-high share capital for a C Corp: does it really matter?
There is said to be a German "lawyer" in the USA who sells American corporations with sky-high share capital ($100 million) and touts them as the ultimate solution.
Of course, it helps that in the USA share capital does not have to be paid in. So founders can go all out here. The sky is the limit.
In the USA, things are completely different. Americans could not care less how much share capital a company has. The figure is not published anywhere. No bank is interested in it. Your business partners will be surprised you even mention it.
I do not know a single American attorney who would ever recommend such high share capital to a client at formation.
LLC, Inc or LP in Delaware, Florida, California, New York, Texas or Wyoming.
6The LLC with a permanent establishment in the USA
Every company we form has a permanent establishment in the USA: an office, employees, a warehouse or management on the ground. For the LLC, that means it becomes taxable in America. The following pages explain what follows from that for tax, for liability and for the obligations year after year.
6.1Forming a US LLC with a permanent establishment
This page is the core of our LLC offering. It explains when an LLC is engaged in a trade or business in the USA: personal services performed in the USA already count, and all the more so a business that continuously sells services, products or goods there. The profit from this business is effectively connected income and is taxed at the regular rates after deducting costs.
If the LLC is owned by a person abroad, it files Form 5472 with a pro forma Form 1120, and the owner reports the profit on Form 1040-NR or, if a company, on Form 1120-F. A multi-member LLC files Form 1065 and withholds tax under Section 1446 on the share of foreign members. If you have no permanent establishment in the USA and do not want one, read on at zerotax.llc.
6.2The LLC as a legal form: a corporate law overview
The overview shows the LLC for what it is under corporate law: a limited liability company with no mandatory governing bodies and no share capital. Ownership, management and profit distribution are governed by the company agreement, the Operating Agreement, which is not filed with any authority. In Delaware, the formation document states only the name, registered office and Registered Agent; members and managers do not have to be listed.
The members are liable only up to their contribution, as long as the company is not run like a personal piggy bank.
6.3What the US LLC is used for
What do entrepreneurs use the LLC for? The obvious use is doing business in the American market, as a standalone company or as part of your group. If you live in a high-tax country as the controlling member, the LLC needs substance in the USA: premises, staff and management on the ground. The page also shows how the LLC can sponsor a visa, how it holds US real estate with limited liability and why entrepreneurs use it to stay out of sight of competitors or customers.
6.4Protecting the US LLC's liability shield
The LLC protects its owners from personal liability for the company's debts. But creditors can pierce this shield. Wyoming law lists the factors a court looks at: fraud, inadequate capitalization, failure to observe legally required formalities and commingling of company and personal assets; apart from fraud, none of these is enough on its own. Four rules keep the shield intact: adequate starting capital, no commingling of finances, signing correctly in the company's name and documenting the business.
The page also explains where the protection ends: with personal guarantees and with your own conduct. And it shows why a missed annual report is dangerous, because some states then administratively dissolve the LLC.
6.5US LLC requirements and compliance
The rules for the LLC are similar in every state but differ in the details: formation time, fees, annual reports and annual taxes. The page compares nine states side by side in a table. Of Delaware, Texas, Florida, Wyoming and New York, only New York requires a written Operating Agreement, within 90 days of formation. We recommend one to every client.
At federal level: an LLC with a single foreign member reports its transactions with that member, even the initial contribution at formation, on Form 5472; failing to do so risks a $25,000 penalty. An LLC classified as a partnership pays no tax itself but files Form 1065, for calendar-year filers by March 15.
7The C Corporation: subsidiary, Inc and conversion
The C Corporation is the most proven US legal form, and we recommend it to most clients. It pays its own tax, 21 percent at federal level, and its shareholders are taxed only on what it distributes. The pages in this section explain the legal form, its uses, formation in Delaware, the obligations and the route from LLC to corporation.
7.1The C Corporation: a corporate law overview
The C Corporation is a stock corporation and can be formed in any state. One person can fill every role: in Delaware a board of one natural person is enough, and one person may hold all offices at the same time. The share capital is up to you and does not have to be paid in. Shareholders are liable only up to their contribution, and their names do not appear in the formation document.
The corporation pays 21 percent federal corporate income tax, plus its state's tax where applicable. Its return, Form 1120, is due on the 15th day of the fourth month after the end of the tax year; Form 7004 extends the filing deadline, but not the payment.
7.2What a US corporation is used for
The obvious use is a US corporation as the subsidiary of your European company for the American market. As a stock corporation it is built for raising capital from investors: it can issue different classes of stock with their own voting rights and preferences. It also serves as the sponsor for a visa or green card, as a holding company over other entities and as the owner of trademark and software rights.
The page also explains when a corporation makes sense because you do not want to be visible to competitors or customers, and why the place where the business is managed helps decide where it is taxed: the company needs real substance in the USA.
7.3Forming a Delaware Inc: founder shares, vesting and 83(b)
This page is written for founders who want to bring investors on board. In Delaware, the Inc is created with the Certificate of Incorporation; the state fee starts at $109 and depends on the shares. Founder shares with vesting are shares subject to a repurchase right. If you are a US taxpayer, you decide within 30 days of issuance whether to make the Section 83(b) election, on Form 15620.
A separate part covers the Delaware franchise tax, which has two calculation methods. Based on the number of authorized shares it starts at $175, under the Assumed Par Value Capital Method at $400, and the lower amount applies. With many authorized shares, the second method is often many times cheaper. The annual report ($50) and franchise tax are due every year by March 1.
7.4C Corporation requirements and compliance
As with the LLC, states differ on formation time, fees, annual reports and yearly charges, and the page compares them side by side. The annual report is not a tax return; it confirms the company's details to the registry. California requires corporations to file the Statement of Information every year, New York the Biennial Statement every two years.
The bylaws, the corporation's internal rules, are not filed anywhere; they are adopted by the founders or the first board. Even so, we advise every client to put them in writing, together with the board's minutes and resolutions. When the corporation pays dividends to shareholders abroad, it withholds tax on them: 30 percent by law, reduced under the applicable tax treaty.
7.5Converting an LLC to a C Corp
Corporate law and tax law are two separate levels: an LLC can become a corporation, or it can stay an LLC and simply be taxed as a corporation. The election on Form 8832 can take effect no more than 75 days back and no more than twelve months ahead; after that, another change is blocked for 60 months. In Delaware, under 6 Del. C. § 18-216 and 8 Del. C. § 265, an LLC becomes a corporation without being wound up and stays the same company, with its contracts, assets and debts.
8The Limited Partnership: the American limited partnership
The LP is the entity for entrepreneurs who want to stay tax-transparent while living in Europe. It is a limited partnership, and with an LLC as its general partner, no one is personally liable without limit.
8.1The LP at a glance under corporate law
The general partner runs the business and is fully liable; the limited partners are liable only up to their contribution. In Delaware, the Certificate of Limited Partnership names the partnership, the Registered Agent and the general partners; the limited partners do not appear in it. We recommend a written partnership agreement in every state, even where the law does not require one.
For tax purposes the LP is transparent: it pays no income tax itself, and its partners pay tax on the profit whether it is distributed or not. The page explains the US tax burden and the withholding tax the LP deducts from the share of foreign partners.
8.2What a US LP is used for
The LP is a versatile entity for doing business in the American market, with individuals or companies as partners. If you are the controlling partner and live in a high-tax country, it needs substance in the USA like any US company: premises, staff and management on site. The page shows how the LP serves as a visa sponsor, how it holds US real estate and why it works well if you do not want to be visible to competitors or customers.
8.3General partner and power of attorney for your US LP
We suggest an LLC as the general partner, so no one is personally liable without limit. Only the general partner then appears in the registry. As a limited partner, you receive a power of attorney that lets you represent the partnership in all matters. The page also covers the company name: the entity suffix stays LP, and a name in your own language can be included if you wish.
8.4US LP requirements and compliance
Formation time and fees for an LP vary by state, and the page compares them in a table. Some states require an annual report, others charge an annual tax instead; California, for example, taxes the LP just like the LLC. At the federal level, the LP files Form 1065 every year, by March 15 for a calendar year, and every partner files their own US tax return.
Two more obligations are often overlooked by founders. If the LP has foreign partners, it withholds tax on their share of the profit from the US business and reports it on Forms 8804 and 8805. And it names a Partnership Representative with substantial presence in the USA to represent it before the IRS; if it does not, the IRS may appoint one.
9Formation, Registered Agent and ongoing obligations
Forming a US company is quick. What comes next decides whether it stays in good standing with its state: the Registered Agent, the company agreement, the annual fees, registration in other states and, at the end, a clean dissolution.
9.1Formation formalities and the formation process
The page describes how formation works with us. You choose the entity type and state, book the product online and then fill in our online form, together with proof of identity. The attorneys on the firm's team draft the formation documents, we file them and provide the Registered Agent in the state of formation. After formation we register the company with the IRS and take care of the accounts; you receive the documents, tax number and account details by email.
How fast the state works depends on the state. In Wyoming, for example, an LLC filed online takes effect immediately; on paper it takes up to 15 business days. After formation, ongoing support begins with bookkeeping, payroll and year-end accounts.
9.2The US LLC operating agreement
The operating agreement is the LLC's company agreement. Delaware, Texas, Florida and Wyoming also accept it orally or implied; New York requires a written agreement within 90 days of formation. It is not filed anywhere; it stays with the company. Where the agreement is silent, state rules apply: in Texas, for example, each person then has an equal vote, and no one can withdraw or be expelled.
The page shows what belongs in it, from management and voting rights to profit allocation, exit and the tax clauses. Others read the operating agreement too: a partnership needs a Partnership Representative, and your home country may classify the LLC based on how the agreement governs management, transferability of interests, profit allocation and capital.
9.3Registered Agent in the USA
The Registered Agent receives lawsuits, official letters and notices for your company and forwards them; Texas calls these its only duties. Delaware, Florida, Texas, Wyoming and California require an agent with a physical address in the state; a PO box is not enough. New York instead names the Secretary of State as the recipient for service of process.
Important in practice: the registered office is not a business address. Formation forms, annual reports and banks ask for the company's principal office or a physical location. If there is no agent, the Secretary of State in Texas becomes the recipient for service, and the state can terminate the company after a deadline; Florida can dissolve it, and Delaware can cancel the Certificate of Formation.
9.4What a US LLC costs per year
The page works out what the six most important states charge every year, and shows which bill only arrives in the second year. Delaware charges $400 a year, Florida $138.75 for the annual report, Wyoming at least $60 and California $800, even in the first year. For a first tax year beginning 2027 to 2029, California charges $400. New York charges $9 every two years; Texas charges no franchise tax up to $2.65 million in revenue, but requires a report every year by May 15. The table below sums it up.
At the federal level, the tax number and the returns cost nothing; it only gets expensive if you miss an obligation, such as Form 5472, with a $25,000 penalty. The ongoing costs are mainly the Registered Agent, bookkeeping and tax returns, and if you do business in a second state, you pay registration and annual fees there as well.
9.5Foreign qualification: registering in a second state
An LLC is only at home in the state where it was formed. If it does business in another state, it has to register there as a foreign LLC. No state gives a final definition of what doing business means. The statutes do, however, list activities that are not enough, such as holding a bank account or selling through independent dealers; in Texas, an office or an employee usually triggers the requirement.
State fees range from $70 in California to $750 in Texas, plus the ongoing obligations in the second state. Without registration, the LLC cannot bring a lawsuit there itself, and it faces penalties and back payments; its contracts remain valid. If your LLC only operates in another state, forming it directly in that state is often the simpler route.
9.6The US beneficial ownership register
The Corporate Transparency Act was meant to require companies to report their beneficial owners to FinCEN. Under the interim rule of March 26, 2025 and the final rule of August 11, 2026, in force since August 14, 2026, companies formed in the US are exempt from this reporting. Only certain companies formed abroad and registered to do business in a state still have to report.
The page explains what this means for your US company, and what still applies: your bank establishes who owns the company when you open the account, and since January 1, 2026, New York requires its own report from LLCs formed abroad and registered in New York.
9.7Dissolving a US LLC
An LLC ends in three steps: dissolution by resolution or event, winding up its business, and cancellation with the state. During winding up, creditors are paid or secured first, including for claims likely to arise within ten years, and only then the members. In Delaware, the Certificate of Cancellation ends the LLC; before that, the full annual tax of $400 for the current year must be paid.
10Taxation of companies and individuals
This page gives you an overview of the US tax system and US tax law
In principle, many elements and types of tax in the US will be familiar to you from home. On the whole, the US tax system tends to be simpler and less complex than many European tax systems.
Worth mentioning here is the US tax reform passed at the end of 2017, the Tax Cuts and Jobs Act. It brought a number of tangible benefits, especially for the self-employed and businesses: since the reform, the federal corporate tax rate has been 21 percent. On the linked page, we cover the key benefits for international US entrepreneurs who are not resident or taxable in the US.
10.1EIN: your company's tax number
Without an Employer Identification Number, there is no business account, no payroll and no tax return. The EIN is free from the IRS, and the IRS explicitly warns against websites that charge for it. You can only apply once the company has been formed with its state. Applying online requires a principal place of business in the US and a Social Security number or ITIN for the responsible person; without both, international applicants apply by phone, fax or mail.
The page walks you through the application step by step, including who is listed as the responsible party. Right after formation comes Form BE-13 for the Bureau of Economic Analysis: it is due within 45 days if a foreign person holds at least 10 percent of the voting rights in a new US company. We handle the application with our EIN Application service.
10.2Taxation of your US corporation
A US corporation pays 21 percent federal corporate tax, plus a separate tax depending on the state. The range is wide: Delaware taxes income from in-state activity at 8.7 percent, Florida taxes a corporation at 5.5 percent, Wyoming has no corporate income tax, and instead of an income tax Texas levies the franchise tax on margin, which for the 2026 and 2027 reports only applies from 2.65 million dollars in revenue.
The page also explains sales tax, which states and local governments levy on sales to end customers, why it is not a VAT, and the contributions for Social Security, Medicare and unemployment insurance once you have employees. Four worked examples show the tax burden in typical scenarios. More on sales tax on the page Sales tax in the USA.
10.3Taxation of your US LLC
A trading LLC with several members is a partnership for tax purposes: it pays no income tax itself, and its members pay US tax on the profit whether or not it is distributed. On foreign members' share of profit from the US business, the LLC withholds tax under Section 1446, for individuals at the top income tax rate; any overpaid tax is refunded with the return.
Individuals can claim a Section 199A deduction of up to 20 percent of their LLC profit, with limits at higher incomes. Depending on the state, there is also income tax or a tax on revenue, sales tax and possibly social contributions.
10.4Taxation of your US LP
An LP is tax-transparent: the partners pay US tax on the profit and file a US tax return, while the LP itself files Form 1065. On foreign partners' share, it withholds tax that is credited against the partners' own returns. The Section 199A deduction cuts the burden for individuals by up to 20 percent of the profit.
11Taking profits out of a US company
Once you have built a successful business in the US, you need to know how to take the profits it has accumulated out of the company or distribute them. We cover this below, starting with the routes that work for every entity type, followed by the pages for corporations, LLCs and LPs.
11.1Your foreign company invoices the US company
You set up a foreign company in a low-tax country that has a tax treaty with the US (Malta or Ireland, for example). It invoices the US company, for example for:
- Head office functions (accounting, logistics, management, marketing, website development)
- Specialist services (you have a software developer you "lend" to the US company for, say, $2,000 a day)
- Rental of specialist machinery, tools, staff (the cameraman in our example at the start rented the cameras owned by his British company to the US company)
- Purchasing company (so that part of the margin is earned in the foreign company)
- License fees (if you own licensable intellectual property)
Each of these invoices has to pass the arm's length test, meaning it must match the price an independent third party would charge.
11.2Loans from the foreign company
The foreign company can lend money to the US company, and the interest can be deducted as an expense in the US company. The arm's length test applies here too: the interest rate has to match what an independent lender would charge for a comparable risk.
11.3Business expenses and investments
Deducting travel and meal costs is not much fun in the US either. By law, business meals are only 50 percent deductible. Other business expenses are treated fairly generously.
Capital assets can be written off immediately, that is, deducted as business expenses. Qualifying assets get 100 percent bonus depreciation, which the One Big Beautiful Bill Act of 2025 made permanent; it was introduced at this level with the 2017 US tax reform. The Section 179 expensing limit for tax years beginning in 2026 is $2,560,000; the deduction phases out to the extent that the year's purchases exceed $4,090,000 (Rev. Proc. 2025-32).
11.4Loans to managers and members
The US company can lend money to its managers and owners. This is not unusual in the US and is fine, as long as the agreement passes the arm's length test.
11.5Salary and company retirement plans
This only makes sense if you live in the US. Take advantage of the lower income tax rates and pay yourself a salary as managing director. Profits put into a company retirement plan are tax-free up to a certain limit.
11.6Stock options
Only if you live in the US: if you grant stock options to employees (and yourself), later gains from exercised options may be taxed favorably for the employee. The gain is then taxed as a capital gain rather than as earned income. Getting the structure right is what counts.
11.7Government incentives
Depending on the size of your US commitment, you can secure government support up front. It is often granted by the state as tax breaks, but also as loan guarantees and grants. On top of that, there are plenty of federal programs. More on the page Incentives for doing business in the USA.
11.8Taking profits out of a US corporation
The page also shows how to reduce the profit available for distribution through invoices and loans from a foreign company, business expenses and immediate expensing, and when salary, shareholder loans, retirement plans and stock options make sense.
11.9Taking profits out of a US LLC
With an LLC taxed as a partnership, the profit is treated for tax purposes as received by the members at the end of the fiscal year, even if it stays in the company account. The members report their share on their US tax return and credit the withholding tax the LLC paid on their behalf. Here too, invoices and loans from a foreign company, business expenses, immediate expensing and salary all reduce the profit. Work out which of these solutions fits before you form the company; in some cases the C Corporation is the better legal form.
11.10Taking profits out of a US LP
The same principle applies to the LP: the profit is taxed at the partner level whether or not it is distributed, and the LP withholds tax for foreign partners and pays it to the IRS. Under the tax treaty, there is usually no further tax in the country of residence if the LP genuinely runs a trade or business in the US. The page shows other ways to reduce the profit, from invoices issued by a foreign company to a company retirement plan.
A clean structure between parent company and US subsidiary, or between you and your US company, coordinated with your accountant.
12How the IRS thinks and works
This section is based largely on my own experience from many years of working in the US. There I ran several companies myself, formed a good number of companies for clients and worked closely with US entrepreneurs, whom I in turn helped gain a foothold in Europe.
It gives you a good look at how the IRS works, but it is certainly not meant as an empirical study. Others will surely have had different experiences. But since my situation matches that of many clients (Europeans forming a company in the US), I hope my impressions carry some weight in this particular context.
Ever since the IRS cracked down hard on Swiss banks and ultimately dealt the deathblow to the famous (or infamous) Swiss banking secrecy, we have known one thing: these guys don't mess around.
Most Europeans are used to a fairly demanding tax office at home. But you do get the impression that the Americans go about it a notch harder and more ruthlessly.
So quite a few entrepreneurs wonder whether doing business in the US already puts one foot in jail. What happens if I make a mistake on my tax return because I don't yet fully understand how things work in the US? What happens if I get bad advice? What happens if I miss deadlines because I had no idea a return was even due?
Questions upon questions. Here I share my own experiences with you, and I hope they give you a realistic picture of the IRS.
12.1The basics
The US has no VAT, so businesses don't report detailed sales figures every month or quarter. That makes the annual tax return the IRS's main tool for getting income and sales information from taxpayers. A huge number of returns land there every year, and only a small share are examined in detail, most of them by mail.
The IRS has three years after a return is filed to assess tax, and six years if the return omits income amounting to more than 25 percent of the gross income reported. For a fraudulent return, or a return that was never filed, there is no time limit.
12.2Tax honesty in America
In my experience, tax honesty among Americans is not exactly stellar. Working off the books is practically a national sport. Even "public servants" such as soldiers and police officers join in without a second thought when there are a few extra dollars to be made.
Then there are people without legal status, who can only be employed off the books anyway. Especially in border towns, but also in big cities like New York, they find low-paid work in restaurants, on farms and in other businesses that need manual labor.
But the problem is far from limited to "lower" income groups. I know at least two attorneys in the US who failed to properly report cash income for years. Both were reported by employees they had let go.
In general, it's completely normal for a great many Americans to have a side job to top up their income. You see it across every social class and profession: teachers who tutor, bankers who broker mortgages on the side, police officers who work security at private events. Some of this adds up to quite tidy sums, sometimes more than the main job pays, and much of it is paid in cash and off the books.
Wherever a large company is involved, though, you can assume everything is handled more or less correctly. If you rent out your home through a platform or work as a driver, you have no chance of escaping the tax man. These companies send so-called 1099 forms to the IRS, reporting once a year how much was paid to independent contractors.
12.3The IRS strategy: shock and awe
Most Americans are completely relaxed about the IRS and don't even make much of an effort to hide or conceal untaxed income. People here are utterly unfazed.
Given the sheer volume of data, it's almost impossible to catch at least the "small" tax cheats, especially the clever ones. That's why the IRS comes down really hard on the ones it does catch. "Shock and awe" is the motto. The idea is to make an example of them, a truly deterrent one. Celebrities, who are clearly in the public eye, are favorite targets for especially tough treatment. The IRS rather enjoys playing its supposed Robin Hood role here.
Campaigns like the one against the Swiss banks are also about deterrence, alongside the big revenue such measures "generate". A zero-tolerance approach is promoted to keep taxpayers at home in line.
For all the saber-rattling, my actual experience is that most Americans and American companies deal with the IRS very rarely or never. You simply can't say the IRS is constantly hounding people and businesses. Even a giant central agency like the IRS couldn't manage that.
12.4Dealing with the IRS day to day as a business owner
As a business owner with employees, you normally deal with the IRS every quarter when you file your payroll tax return on Form 941. On it, you report the income tax withheld and the Social Security and Medicare contributions for the past quarter. Depending on the amount, you pay the taxes themselves monthly or semiweekly.
It is absolutely essential that the quarterly return is always filed on time and that payments to the IRS go out by the deadline. Deadlines are taken very seriously, and the IRS is pretty quick off the mark when it comes to levying bank accounts. If in doubt, file a return on time and correct it later rather than not file at all.
The same goes for the annual tax return and the estimated corporate income tax payments during the year if you expect a profit. You can extend the deadline for the annual return with Form 7004, but not the deadline for payment.
If you follow these rules, chances are you won't hear from the IRS at all for many years and may never be audited, especially if you don't live in the US yourself and the company is taxed as a corporation.
What draws the IRS's attention and makes contact more likely is anything that deviates from the norm and looks a bit fishy. For example:
- Large loans to management
- Losses over several years
- Large cash transactions
- Figures out of proportion (revenue $100,000, travel expenses $50,000; or revenue $50,000, charitable donations $10,000)
- Real estate losses
Certain industries are also viewed with general suspicion, used car dealers for example.
12.5If you do end up dealing with the IRS
If for any reason you need to speak with the IRS, in my experience it's best to keep the following in mind from the start:
- The agent's knowledge is extremely limited.
- The agent has never been abroad and may never have left their home state.
- The agent knows their procedures inside out. They use specific terminology. They have a specific view of the world.
- There's no point trying to communicate outside the agent's vocabulary and frame of reference.
Go into the conversation with this understanding, adjust how you act accordingly, and you'll be amazed how quickly you reach an agreement. If there's a more serious problem you can't solve yourself, bringing in a specialized attorney is usually highly advisable. For IRS letters and penalties, we offer our IRS Letters and Penalties service.
13Which state is the best location for my business?
Anyone planning to start a business in the US quickly faces the question of which state the company should be based in. Opinions vary widely, and emotions often play a bigger role than facts.
My view: decide on the best business location purely on practical and commercial grounds. It makes no sense to set up a company in Wyoming just because there's no state corporate income tax. Sure, if you're a rancher, Wyoming is lovely. But when it comes to accessibility, visibility, proximity to your market and hiring good people, places like that are at a clear disadvantage.
Start by asking yourself these questions:
- Where do I like it best?
- Where are my customers?
- Do I benefit from having lots of other players in my industry nearby (Silicon Valley, Wall Street)?
- Where will I find employees?
- What image do I want my choice of location to project?
- How easy is the location to reach? From Europe? From within the US?
- Are the location costs (rent, wages) in proportion to the revenue I expect?
I'd argue that 90 percent of all businesses can make the right location decision just by answering these simple questions. In my experience, the remaining 10 percent are special cases: large companies receiving incentives, regulated industries, the EB-5 visa or the acquisition of an existing business. The page on choosing your state covers them and also explains why the state of registration and the place of management can be in different states.
13.1The best state for your LLC
For an LLC with a real business, the answer is usually the state where you actually work. Form it somewhere else and you have to register the LLC there as well, which means paying two states. This page compares Delaware, Wyoming, Florida, Texas, California and New York on formation and ongoing costs. Wyoming and Delaware are affordable and discreet; California, at $800 a year, and New York, with its publication requirement, are expensive. Florida, Texas and Wyoming levy no state income tax on individuals.
Delaware pays off when investors, several members or a future holding company need that state's law. In practice, a visa, where you live and who your customers are usually settle the question long before any fee table does.
13.2Which state, which entity type?
This page brings together the two basic formation questions for commercial US companies with a permanent establishment, whose profits are fully taxable in the US. As a rule, we recommend the C Corporation; a partnership only if there are further good reasons, and then an LP rather than an LLC. On state tax, the page shows which states are favorable depending on entity type and revenue, including Wyoming with no corporate income tax and Texas with its franchise tax, which only applies above a revenue threshold. For most businesses, though, operational questions are what decide it.
13.3The states and cities we recommend
We support you anywhere in the US. When asked, we recommend five cities, each with its own profile: Austin and San Francisco for tech, New York City for finance, Miami as the gateway to Latin America, and Wilmington, Delaware, for your registered office. The page introduces each one and explains why location drawbacks such as high taxes can usually be offset by business success, but rarely the other way round. If Texas is your goal, you will find formation there under Company formation in Texas.
14Delaware: where corporations make their legal home
No state comes up more often when people talk about forming a company. More than 2.28 million entities are registered in Delaware, including more than two thirds of the Fortune 500. Five pages explain what lies behind this and who Delaware is right for.
14.1Forming a Delaware LLC for a real US business
A Delaware LLC is created by filing a Certificate of Formation with the Division of Corporations. The state charges $110, and the document lists only the name, registered office and Registered Agent. The LLC Agreement is not filed. Delaware gives it the greatest possible freedom of contract, even allowing fiduciary duties to be limited; only the duty of good faith and fair dealing remains. Every year the LLC pays $400 in tax by June 1 of the following year. There is no annual report, but late payment brings penalties and the loss of good standing.
The page also explains the flip side: if you run the business in Texas, Florida or California, you register the Delaware LLC there as well and carry the obligations of both states. In Delaware, a member's creditor can only reach the LLC through a charging order on the member's distributions, even when there is just one member.
14.2Why Delaware is so attractive to big corporations
How did this small state become the legal home of big corporations? The page tells the story of the race among states to attract companies and explains what draws corporations to Delaware: sophisticated corporate law, an administration built around business, and the Court of Chancery. This business court is more than 225 years old, has written much of modern US corporate law, and appeals go straight to the state's Supreme Court.
It also explains why the advantages mainly apply to large corporations, and only at state level: a Delaware company changes nothing about federal tax.
14.3Delaware for Dummies: the tax haven, explained simply
Is Delaware a tax haven? The page busts the myth. Delaware taxes income from activities and assets in the state at 8.7 percent corporate income tax. A corporation is exempt if its activity in Delaware is limited to holding and managing investments, receivables, patents and trademarks. Federal tax of 21 percent still applies.
The Delaware register publishes neither the members nor the managers of an LLC, but Delaware is not alone in that. Anonymity ends at the latest when you open a bank account, because the bank establishes who owns the company.
14.4The Delaware flip
In a Delaware flip, a new Delaware holding company is placed on top of the foreign company, often in connection with a venture capital funding round. The reasons: the huge US venture capital market, a possible IPO on a US exchange, a later sale to US investors, and investors who know how a Delaware corporation works.
Technically, the flip usually runs as a share exchange: the shareholders then hold the Delaware corporation, the foreign company becomes its wholly owned subsidiary, and options are swapped for options in the new parent. The tax side of a flip is complex; the goal is a tax-neutral restructuring. The page also covers the downsides, and why the earlier you look at a flip, the simpler it is.
14.5Delaware: The First State
This profile shows Delaware as a place, not just an address on a register: its location in the Mid-Atlantic region, its economy with its focus on chemicals, and taxes for businesses and individuals. If you are thinking of not only forming a company in Delaware but also working there, this gives you an overview of the state itself. Formation there is covered on the page Company formation in Delaware.
15Wyoming, Texas, Florida, New York and California
These are the five other states our clients ask about most. Each has its own forms, deadlines and fees, and each has a quirk that catches founders by surprise. The table at the end of this section puts all six states side by side.
15.1Forming a Wyoming LLC
In 1977, Wyoming became the first state to write the LLC into law. The formation sequence is fixed: check the name, appoint a Registered Agent with a Wyoming address, file the Articles of Organization, sign the Operating Agreement, then apply for the EIN. Filed online, the LLC takes effect immediately, and the state fee is $100. Wyoming levies no income tax, on companies or individuals, and no franchise tax.
Every year, on the first day of the month of formation, the annual report and license tax are due, at least $60. If nothing has been filed 60 days later, the state administratively dissolves the LLC. And wherever the business actually operates, for example with an office or staff in Texas, the LLC must also register there as a foreign entity.
15.2Forming a Texas LLC
A Texas LLC is created by filing a Certificate of Formation (Form 205) with the Secretary of State; the fee is $300. The name must be distinguishable from existing names and contain "Limited Liability Company", "Limited Company" or an abbreviation of either. A Registered Agent with a Texas street address is mandatory; the LLC cannot act as its own agent.
The LLC is subject to the franchise tax. Up to $2.65 million in revenue, none is due for the 2026 and 2027 reports, but the Public Information Report is still due every year by May 15. Under its constitution, Texas levies no income tax on individuals, including on their share of partnership income. If you sell goods, you register for sales tax: 6.25 percent for the state, plus up to 2 percent for local governments.
15.3Forming and running a Florida LLC
A Florida LLC is created by filing Articles of Organization with the Division of Corporations; the state charges $125, including the Registered Agent designation. Every year between January 1 and May 1, the annual report is filed online with the state for $138.75; after that, a $400 late fee is added, which cannot be waived. Florida has no income tax on individuals; only an LLC taxed as a corporation pays corporate income tax.
If you sell in Florida and have employees, register for sales tax (6 percent for the state, plus a county surtax) and reemployment tax before you start, and obtain local business tax receipts from the county and city. Since July 1, 2026, a Florida LLC can create protected series. For a single-member LLC, the law may in some circumstances allow creditors to have the membership interest sold.
15.4Forming a New York LLC
A New York LLC is created by filing Articles of Organization with the Department of State, state fee $200. Then comes a requirement no other state has: within 120 days, the formation must be published for six weeks in two newspapers in its county, one daily and one weekly, and the LLC files a Certificate of Publication, fee $50. Miss the deadline and its authority to do business in New York is suspended; contracts remain valid, and filing the proof late lifts the suspension.
A written Operating Agreement is required within 90 days of formation, and the Biennial Statement every two years for $9. If the LLC has New York income, it pays an annual filing fee to the state tax department, from $25 to $4,500.
15.5California LLC: the costs
A California LLC costs $70 to form, plus $20 within 90 days for the Statement of Information, which then recurs every two years. The $800 annual tax is due for every tax year, including the first, initially on the 15th day of the fourth month after filing; if the first tax year begins in 2027 through 2029, it is $400 in the first year. From $250,000 in California income, the LLC fee is added, tiered up to $11,790.
An LLC from Delaware or any other state also pays the annual tax as soon as it does business or is registered in California. It keeps running until the LLC is cancelled with the Secretary of State; if you cancel using the short form within twelve months of formation, you pay nothing for the first year.
| State | Formation (state fee) | Every year | Due |
|---|---|---|---|
| Delaware | $110 | $400 tax, no annual report | June 1 of the following year |
| Wyoming | $100 | Annual report with license tax, at least $60 | First day of the month of formation |
| Texas | $300 | Public Information Report; franchise tax only above $2.65 million in revenue (2026 and 2027 reports) | May 15 |
| Florida | $125 | Annual report $138.75 | January 1 to May 1 |
| New York | $200, plus publication and $50 for the proof | Biennial Statement $9 every two years | in the month of formation |
| California | $70, plus $20 for the Statement of Information | $800 annual tax, including the first year; Statement of Information every two years | 15th day of the fourth month |
Source: Delaware Division of Corporations (fee schedule, Alternative Entity Tax Instructions); Wyoming Secretary of State (Business Fees, FAQ); Texas Secretary of State (Form 205) and Texas Comptroller (franchise tax); Florida Statutes § 605.0213 and Division of Corporations; New York Department of State; California Secretary of State and Franchise Tax Board. Retrieved October 24, 2026.
16Holding companies: who sits above your US companies
As soon as there is more than one company, the question is who sits at the top. A holding company holds and manages the shares, while the subsidiaries do the business. Whether it is based in the US or abroad determines tax, inheritance and confidentiality.
16.1Delaware holding company for entrepreneurs and families
A Delaware holding company holds the shares of your US companies; the subsidiaries do business in the state where they operate. For the group to file a consolidated tax return, you need a US corporation at the top holding at least 80 percent of the vote and value of each subsidiary; your company back home cannot take on this role, because foreign companies cannot be part of the group. In Delaware, the holding corporation pays $50 for the annual report and Delaware franchise tax from $175; there is no state corporate income tax if it only holds and manages investments there.
If family members without US residence hold the holding company's shares directly, those shares count as US assets for US estate tax; a return is due from as little as $60,000 in US assets, and tax treaties may help. Form 5472 and the BE-13 report come with every foreign-owned holding company. We handle the formation with our Delaware Holding Company service.
16.2International holding companies
This page looks beyond the US. It distinguishes between the US holding company, the international holding company above the US company, for example in the United Kingdom or Malta, and the holding company for intellectual property. A holding company earns from dividends and sales of shareholdings, as well as from loans, management services and licenses to its subsidiaries. The subsidiaries' profits are taxed in their home state before distribution; a holding company is not a tool for minimizing operating profits.
The page explains when an international holding company as parent of the US company solves the US estate tax issue, and what the OECD and EU rules against profit shifting mean for holding companies that hold intellectual property.
17What you need to know about US banking
The US has its big national banks and then countless regional banks, similar to local savings banks in Europe, except that they are privately owned. On top of that come fintech providers that run accounts through partner banks.
American banks are straightforward but often old-fashioned. Checks play a bigger role in everyday life than in Europe, and banking apps let you deposit a check by taking a photo of it. Generally, banks have a strong US focus. Anything beyond their own backyard is complicated, and some small banks are poorly set up for transfers from abroad.
17.1What the bank wants to see when you open an account
Opening an account for your US company is possible for non-Americans too. Under Treasury rules, the bank must record a physical address for the company (its headquarters, an office or another location) and identify the beneficial owners: everyone holding at least 25 percent, plus one person who controls the company. You also need the formation documents, the EIN and an ID.
Our formation packages include the account. By default, we open a USD business account for your US company through Mercury. Mercury is a fintech company, not a bank itself; the accounts are held by partner banks whose deposits are FDIC-insured up to at least $250,000 per depositor, ownership category and bank. You don't need to live in the US for this, but you do need a company formed in the US with existing or planned business there. Learn more under Bank account for your US LLC, US LLC and Mercury and on the US Bank Account Opening page.
17.2Loans and credit lines
Once your American company is doing well and generating revenue, a line of credit (overdraft facility) is realistic. The credit line goes to your company, not to you personally, and you don't have to live in the US to get it. Some banks are skeptical, though, if you don't live in the US and therefore have no US credit history.
Three factors decide: the company's credit score, the revenue on its account, and soft factors such as the business model and substance in the US. The company's score starts with the D-U-N-S number, a free nine-digit identifier from Dun & Bradstreet, and grows with contracts you pay on time against invoice. Loans guaranteed by the Small Business Administration, however, are ruled out as soon as the company is wholly or partly foreign-owned. How to build your company's creditworthiness is covered under Business credit in the USA.
17.3US PayPal account
A US PayPal business account is an option for your newly formed US company, in addition to the business bank account. It lets you accept online payments from customers and send money to others. Profit distributions still go through the company's regular US business account. The page explains what you need for the account and how it works alongside the business account.
17.4Automatic exchange of information
Many clients ask whether their tax authority at home will find out about an account held by the US company. How automatic exchange of information under the OECD Common Reporting Standard works, and the separate path the US takes with FATCA, is explained on the page USA, CRS and FATCA. Either way, our approach is the same: your US company is a company doing business in the US, properly reported there and at home.
Your own access to the American financial system, even without an SSN.
18America as a police state: fiction or reality?
During my time in the US, I've met a lot of police officers, as well as judges, prosecutors and all kinds of court clerks and officials in several states (hint: speeding!). My experiences have been nothing but good. I've always been treated with friendliness, courtesy and respect.
At the same time, the US imprisons more people relative to its population than almost any other country in the world: according to the World Prison Brief, 542 per 100,000 residents (end of 2023). "Law and order" politics enjoys broad public support. If you don't follow the rules, you should be locked up.
18.1Law and order
This mindset also has its roots in the "zero tolerance" policy Mayor Rudy Giuliani used to fight crime in New York in the nineties. The other side of the picture is the reports of police violence that keep making headlines.
18.2The problem of social inequality
It is mainly the disadvantaged who suffer under these conditions. The middle class rarely has negative encounters with the police, except, as in my case, through traffic offenses like speeding. People have a thoroughly positive view of the police and are glad when officers are visible.
In my view, the abuses and the quick reach for the gun have two causes:
- Poor training. The officer doesn't know how to defuse a critical situation and reaches for his gun.
- Military background: Many veterans become police officers after active duty. Old habits die hard, and adjusting from the battlefield to a small town isn't easy.
18.3What this means for European entrepreneurs
As a European entrepreneur, you have little to fear from American police and can, on the contrary, expect courteous treatment. The US is a huge country. If you live in Oslo, police violence in Sicily barely touches you.
But if you're caught using drugs, or even drinking and driving, you're in trouble regardless of your social class: you may spend a night in jail and face real court proceedings.
And only one thing helps then: hire the best lawyer you can afford. Unlike back home in Europe, almost everything in the US depends on a good lawyer. Good lawyers are expensive, so those who benefit most from the US legal system are the ones who can afford them.
18.4Don't just pay the ticket
By the way, I've always fought every ticket through a lawyer instead of simply paying the fine. I won four out of five cases, was "acquitted" and didn't have to pay in the end. How is that possible?
Well, when a ticket is actually contested rather than simply paid, the police department has to put together a file and send the officer to court as a witness. This is tackled with fairly little enthusiasm unless it's a serious matter. As a result, the ticket is often dropped.
19Does America's "sue culture" really exist?
Every entrepreneur opening a business in the US wonders: will I constantly be sued by unhappy customers and employees?
Everyone knows the media stories about absurd damages lawsuits in America, like the one over hot coffee from a fast-food restaurant.
19.1Who sues whom, and why?
"Being sued" can mean three different things:
- Non-performance and breach of contract: Say a customer orders a service from you (installing a kitchen, for example), and in the customer's view you don't deliver on time or only deliver part of what was agreed. The customer takes action for non-performance and wants all or part of their money back. In my experience, even if the customer brings in a lawyer, these cases almost always settle and never reach court.
- Damages (property damage): Shortly after you install that kitchen, a pipe bursts and floods the customer's home. The customer holds you responsible and expects compensation.
- Damages (personal injury): The customer slips in the flooded kitchen, breaks a leg and sues you for damages.
In my experience, lawsuits over non-performance, breach of contract and property damage are about as common as they are in Europe, so not exactly an everyday occurrence.
Good work, clear agreements, written contracts and good communication help a lot here. And if something really does go wrong, liability insurance will cover you in many cases. As always, a good lawyer is worth their weight in gold when things get serious. If you sell products in the US, also read the page on product liability.
19.2Ambulance chasers and the pizza delivery guy
When it comes to personal injury, the US definitely has a sue culture. Personal injury lawyers are scornfully called "ambulance chasers." They work for their clients on a contingency basis and take a large share of the damages paid out.
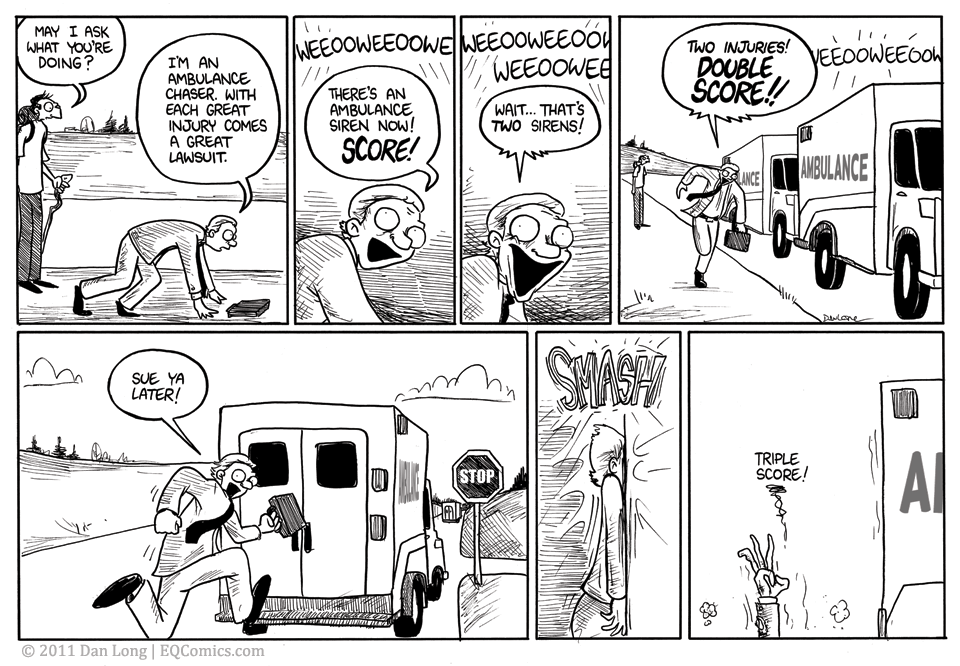
Here is a real example from our practice: a client runs a pizza restaurant. His delivery driver falls off his own moped and gets a few scrapes. The driver sues the client, claiming there were too many pizzas in the insulated box and that this made him lose his balance.
The young man hires an "ambulance chaser", who demands $20,000 in damages from the client. In the end they settle on $800 for pain and suffering. The client pays through gritted teeth, because $800 is less than the fee he would end up paying his own attorney.
19.3Reality check
But let's be clear: small and mid-sized businesses do not get hit with damages lawsuits every day. What we hear about in the media are extreme exceptions. I know more attorneys who flatly turn down personal injury cases because they aren't worth it than I know business owners who have been successfully sued for damages.
Lawmakers are aware of the problem, and some states limit damages lawsuits for certain industries by law. Texas is a good example: in medical malpractice cases, damages for pain and suffering against doctors are capped at $250,000 per plaintiff. How well employers are protected against lawsuits from their employees is explained on the page Protection against employee lawsuits.
20Your path to a green card or US visa
Learn more about visa options for business owners on this page
Living in the USA, at least for a few years: for many business owners, that's a dream. The often unflattering coverage of the USA in European media does little to change that. And let's be honest: the USA has a lot to offer, especially if you're not entirely without means. For business owners in particular, the USA offers huge economic opportunities that are much harder to realize in Europe.
Whether your interest in living in the USA is about business or something more personal (adventure, perhaps?): the move needs careful planning and comes with its own challenges. And first and foremost comes the visa that lets you live in the USA. Be prepared for a long and often complicated administrative process.
But here's the good news: running a business in the USA is the easiest way to get a green card or visa that lets you live there. As a basic principle, understand that to get a US visa as a business owner, you need to create tax revenue and jobs for Americans. That is what's expected of you. If there's a substantial business abroad behind your US company, the route is usually the L-1 visa; otherwise it's the E-2 investor visa.
Learn more about visa options for business owners and health insurance coverage in the USA. You'll find an overview of all of the firm's company formation services under Formation.
- Three first-hand stories show why business owners go to the USA: for the market, as a second pillar and for a life in America.
- This guide is for business owners who serve the US market, expect at least $250,000 in annual revenue and will build an operation with premises and staff within 12 to 18 months. Shell companies are not our thing.
- The LLC, C Corporation and Limited Partnership are the entity types that matter. Every company we form has a place of business in the USA, and each one comes with a Registered Agent, annual obligations and IRS filings.
- Profits come out through invoices from a foreign company, loans, salary, company retirement plans and stock options from the US company; capital goods can be written off immediately.
- Choose your location for practical reasons; Delaware, Wyoming, Texas, Florida, New York and California differ in fees and obligations. Plus: holding companies, bank accounts, experiences with the IRS, the police and the lawsuit culture, and the path to a visa through your own business.
Frequently asked questions
Who is this guide for?
For business owners who want to start a US company to serve the American market, expect at least $250,000 in annual revenue and will build an operation with their own premises and staff in the USA no later than 12 to 18 months after formation. If you're looking for a shell company, you're in the wrong place.
Which entity types work for a business in the USA?
The most common are the Limited Liability Company (LLC) and the C Corporation, and we also recommend the Limited Partnership (LP). An LLP or S Corp is not relevant for most clients. The features of each entity type apply regardless of the state.
Does a US corporation need a lot of share capital?
No. In the USA, share capital doesn't have to be paid in, it isn't published anywhere, and no bank cares about it. Share capital of $100 million is a marketing gimmick.
How do you get profits out of the US company?
For example, through invoices from a foreign company for administration, specialists, rentals, purchasing or licenses, through loans from the foreign company and, if you live in the USA, through salary, company retirement plans and stock options.
Which state is the best location?
The one that makes sense for practical and business reasons: where your customers are, where you can find staff, how easy the location is to reach and whether the costs fit the expected returns. No state corporate income tax on its own is not a reason. If your company operates in a state other than the one it was formed in, it also registers there.
Does a business in the USA help with a visa?
Running a business in the USA is the easiest way to a visa or green card that lets you live there. You're expected to create tax revenue and jobs for Americans. The visa itself is decided by the US authorities.
How we help you
- US Company FormationLLC, Inc or LP in Delaware, Florida, California, New York, Texas or Wyoming.
- US market entrySubsidiary, staff, taxes: your start in the US market.
- Form a CorporationThe US corporation (Inc) for growth, investors and your visa.
- Form an LLCThe US LLC with a permanent establishment, turnkey in six states.
- Form a Limited PartnershipThe US LP for structures with a general partner and limited partners.
- Tax structureA clean structure between parent company and US subsidiary, or between you and your US company, coordinated with your accountant.
- US Bank Account OpeningYour own access to the American financial system, even without an SSN.
- Delaware holdingThe holding above your US companies, with one consolidated tax return.
- Visa Roadmap for Company FormationFormation and visa in one plan, so the company carries the visa.
- Company formation consultationEntity type, state and tax consequences, before you commit.
All guides on this topic
 Delaware for Dummies 2026: the US tax haven, finally explained Read more →
 Why Delaware is the favorite home state of big US corporations Read more →
 How to set up a nonprofit in the USA Read more →
 Protect your US LLC's liability shield & avoid the risks Read more →
 Common US business entities at a glance Read more →
 Forming a company in the USA: which state is the best home? Read more →
 The US beneficial ownership register Read more →
 Our recommended states & locations Read more →
 Forming a US company: which state? Which entity type? Read more →
 Formalities & steps for forming your US company Read more →
 Quick check: which US entity type is best for me? Read more →
 Delaware: The First State Read more →
 Compliance in the USA: C Corporation obligations by state Read more →
 Corporate requirements & compliance for the US LLC Read more →
 Corporate requirements & compliance for the US LP Read more →
 The best state for your LLC: usually the one you work in Read more →
 California LLC costs: $70 to form, $800 in year one Read more →
 Delaware holding company for entrepreneurs and families: who sits at the top Read more →
 Forming a Delaware LLC: from the Certificate of Formation to $400 a year Read more →
 Forming and running a Florida LLC: from the annual report to sales tax Read more →
 Foreign qualification: when your LLC does business in a second state Read more →
 Forming and managing international holding companies Read more →
 Forming a Delaware Inc: founder shares, vesting and the 83(b) deadline Read more →
 Dissolving a US LLC: wind up first, then cancel Read more →
 Converting an LLC into a C Corp: three routes and how the IRS sees them Read more →
 New York LLC: six weeks in two newspapers and the 120-day deadline Read more →
 The US LLC operating agreement: the contract everyone reads Read more →
 Registered Agent in the USA: who accepts a lawsuit for your company Read more →
 Taxation of your US Corporation Read more →
 Forming a Texas LLC: from your name at the Secretary of State to May 15 Read more →
 What a US Corporation can be used for Read more →
 Taking profits out of your US Corporation Read more →
 The US C Corporation as an entity: formation, officers, liability Read more →
 Getting credit in the US: a line of credit for your company Read more →
 Taxation of your US LLC Read more →
 What your US Limited Liability Company (LLC) can be used for Read more →
 Annual cost of a US LLC: what six states charge Read more →
 Taking profits out of your US LLC Read more →
 Forming a US LLC with a permanent establishment: what the IRS then requires Read more →
 The US LLC as an entity: what an LLC is and how it works Read more →
 Taxation of your US Limited Partnership (LP) Read more →
 What your US Limited Partnership (LP) can be used for Read more →
 Taking profits out of your US LP Read more →
 General partner and signing authority for your US Limited Partnership (LP) Read more →
 The US Limited Partnership (LP) as an entity at a glance Read more →
 US PayPal account Read more →
 Which US entity is best for me in 2026? Read more →
 Forming a Wyoming LLC: step by step from filing to EIN Read more →
More on forming a US company
All articles → Delaware for Dummies 2026: the US tax haven, finally explained Read more → Why Delaware is the favorite home state of big US corporations Read more → Protect your US LLC's liability shield & avoid the risks Read more → Common US business entities at a glance Read more → Forming a company in the USA: which state is the best home? Read more →